
Europe – Development Pipeline
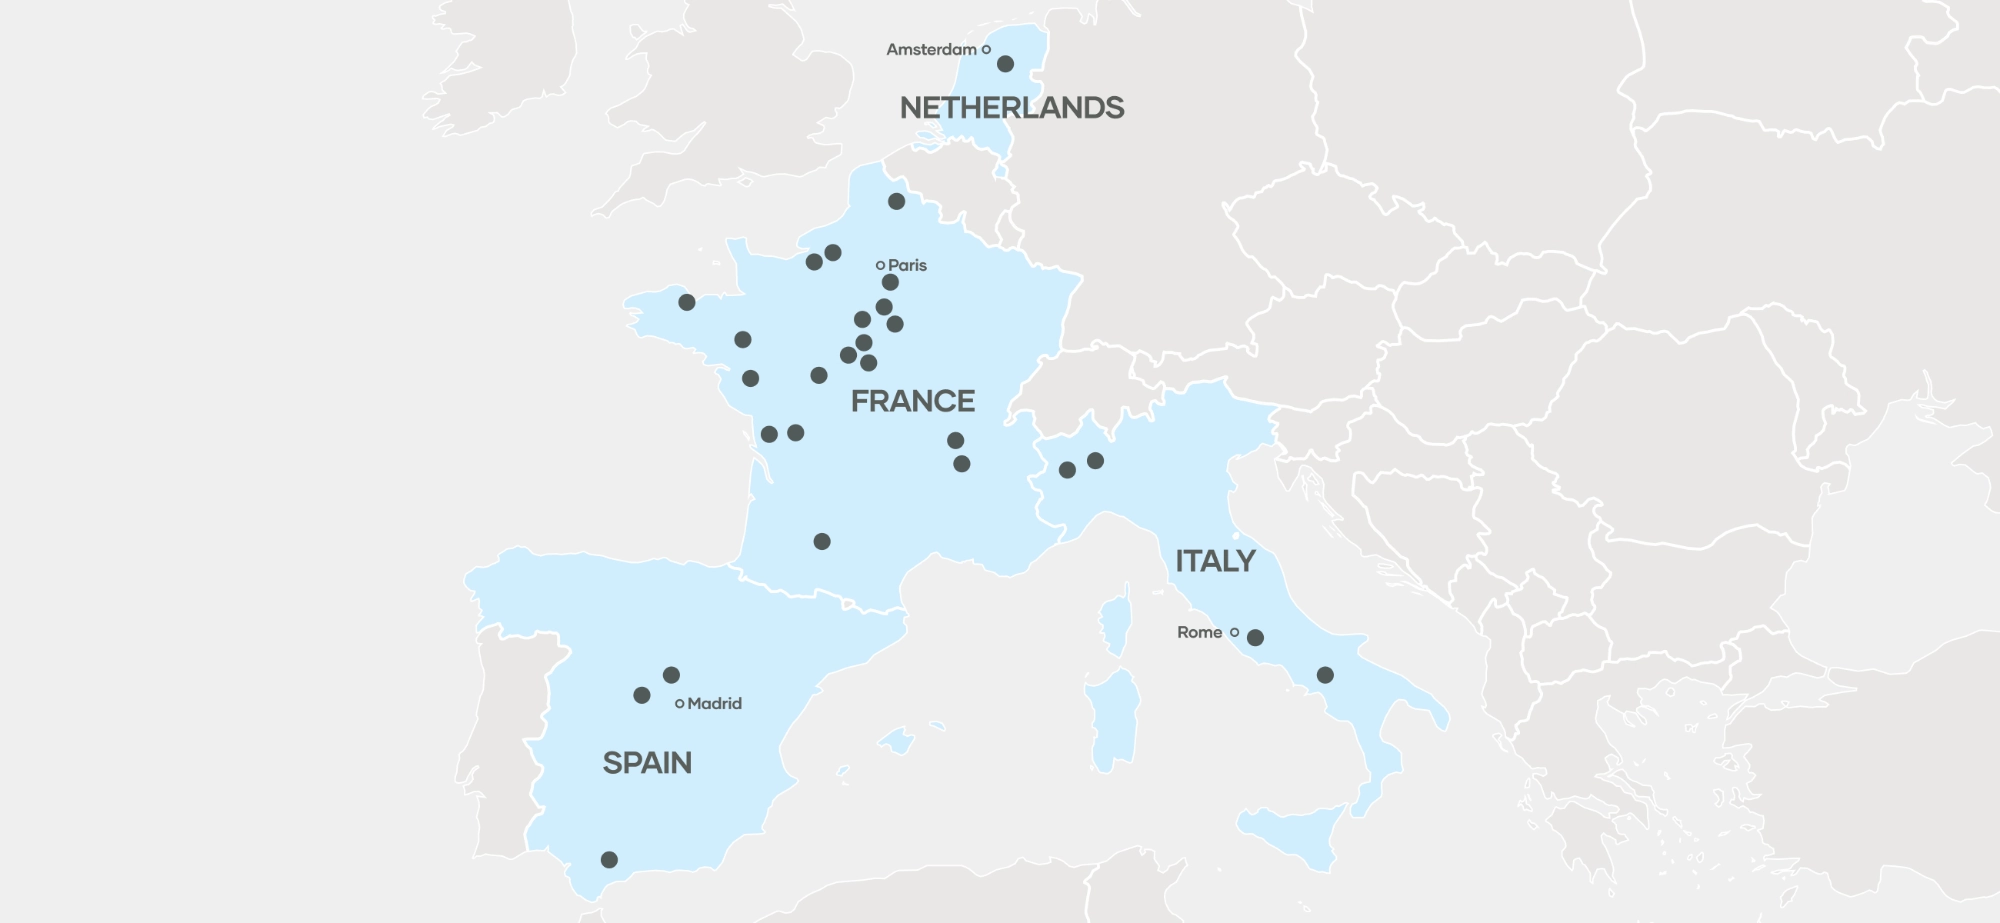
France
France is the second largest economy in the euro area and one of Europe’s deepest consumer markets, with a population of around 68 million. Distribution is organised along a single spine running from Lille through Île-de-France and Orléans to Lyon and Marseille, where the majority of large scale logistics take up occurs. Île-de-France alone holds some 12 million people and is the largest urban consumer market in continental Europe, while Lyon commands the Rhône corridor and Marseille provides the principal Mediterranean gateway.
Supply is tightening structurally. The Climate and Resilience Law commits France to net zero land artificialisation by 2050, with land consumption to halve before 2031. Consented land in established locations is an increasingly scarce asset, and France’s mature third party logistics sector provides depth of institutional grade covenants across food, retail, ecommerce and industrial distribution.
Italy
Italy is the third largest economy in the euro area, with logistics demand heavily concentrated in the north. The industrial triangle of Milan, Turin and Genoa generates a disproportionate share of national output, with Lombardy alone contributing roughly a fifth. Milan is the demand centre, with Novara and the Piedmont corridor sitting on the axis toward Turin and the rail route into Switzerland. Genoa and the Ligurian ports form Italy’s principal maritime gateway and the southern terminus of the Rhine to Alpine corridor, connecting northern Italy to pan-European distribution.
The market is defined by scarcity. Modern institutional grade stock is limited relative to the size of the economy, and municipal level planning lengthens delivery timelines and rewards operators controlling consented land. Demand is underwritten by a large export oriented manufacturing base alongside ecommerce, where penetration remains below the European average and is growing quickly.
Netherlands
The Netherlands is Europe's principal gateway market and one of the most productive logistics economies in the world. Rotterdam is Europe's largest seaport and Schiphol one of its busiest air freight hubs, placing much of the northwest European consumer market within a day's drive of a single Dutch base. Distribution runs along the corridor from Rotterdam through Tilburg and Venlo to the German border, where it connects to the Rhine and the industrial demand of the Ruhr. Occupier demand concentrates on these nodes alongside Schiphol, where infrastructure, labour availability and accessibility converge, and take up continues to grow.
Scarcity works in favour of established positions. Land for large scale logistics is tightly controlled at provincial level and electricity grid capacity is allocated ahead of demand, so consented and powered sites carry real and rising value. The market rewards quality: rents on modern, sustainable space continue to grow while older stock falls away. Demand is underwritten by the world's most mature third party logistics sector and by European distribution centres choosing the Netherlands as the single point from which to serve the continent.
Spain
Spain has a population of close to 48 million and one of Europe’s largest manufacturing bases, concentrated across Catalonia, Valencia, Aragón and the Basque Country. Logistics demand is anchored on three markets. Madrid accounts for roughly a fifth of national output and is served by the Henares corridor along the A-2, where availability has tightened sharply. Barcelona combines a metropolitan population of around 5 million with its port and the land bridge into France, while Valencia adds the busiest container port on the western Mediterranean.
Ecommerce penetration remains below northern European levels and continues to converge, and nearshoring is directing manufacturing and inventory back into Iberia. Prime rents remain well below France, the Netherlands and the United Kingdom, leaving a longer runway for rental growth.